
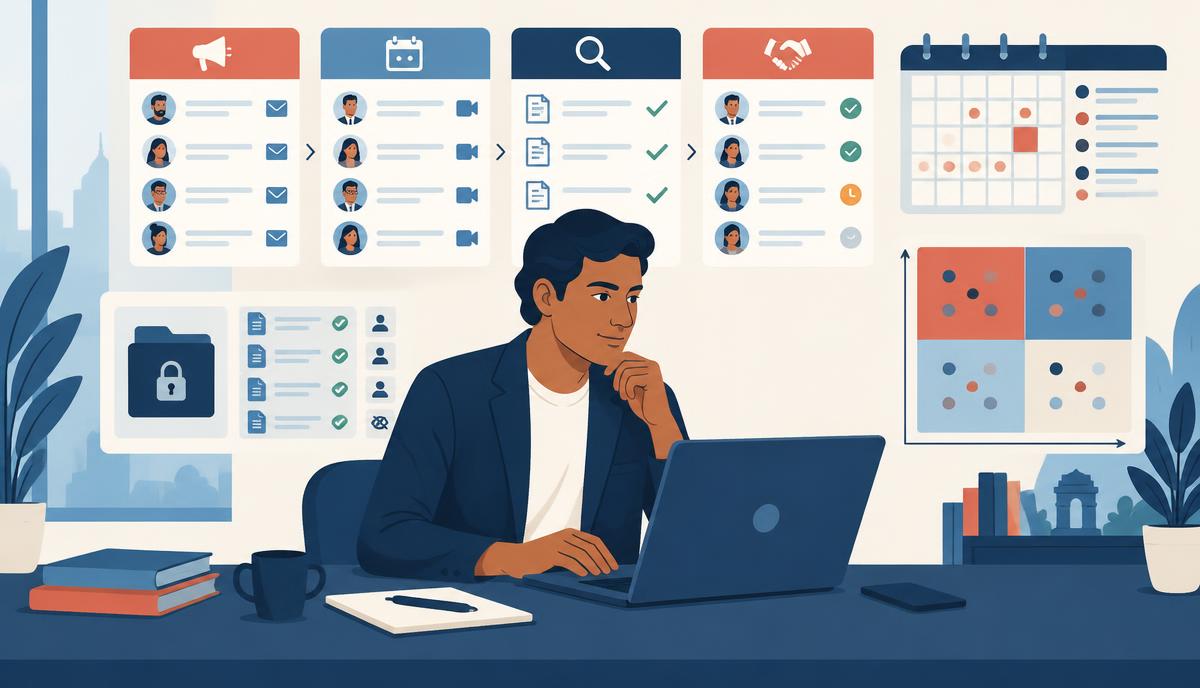
Pipeline Architecture: Defining Distinct Funnel Stages
Once you complete your initial research and compile a targeted institutional shortlist using structured methods outlined in our guide on how to find investors for startup ventures in India, the fundraising process shifts from discovery to active deal management. Operating an active raise without a dedicated pipeline framework leads to dropped follow-ups, misaligned communication, and lost institutional momentum.
- Lead / Identified: The fund or angel is shortlisted, thesis alignment is verified, and mutual connections are identified.
- Contact Initiated / Warm Intro Queued: A connector has agreed to introduce the company, or an initial introductory note has been sent.
- First Meeting Scheduled / Held: The initial introductory narrative has been presented, establishing baseline business context.
- Active Diligence (Commercial / Technical): The investment team reviews operating metrics, customer references, market models, and the core pitch materials.
- Partner Meeting / Investment Committee (IC): The deal sponsor presents the thesis to the broader partnership for formal capital allocation review.
- Term Sheet Negotiation: A preliminary or binding term sheet has been issued, triggering structural alignment on valuation, board seats, and rights.
- Legal Diligence & Closing: Definitive documentation, share subscription agreements, and bank escrow workflows are executed.
Startups must avoid treating stages loosely. An investor reviewing an introductory teaser is fundamentally distinct from one evaluating a multi-tab financial model. Mapping clear exit criteria for each stage ensures founders avoid premature optimism.
Logging Interactions: Contextual Notes, Action Items, and Ownership
Institutional memory degrades quickly when a founding team manages multiple conversations simultaneously. Every investor touchpoint must be logged immediately with structured notes, explicit ownership, and clear deadlines. Relying on memory between partner calls guarantees missed deliverables.
A standard interaction log must capture four mandatory operational components for every meeting or email exchange:
- Participant Context: Names, seniority, functional specialisations (for example, fintech partner vs associate), and previous portfolio investments of the attendees.
- Key Questions & Objections Raised: Granular queries regarding unit economics, customer concentration, or distribution strategy.
- Action Items & Deliverables: Commitments made during the call (such as providing a retention cohort or technical architecture memo) along with assigned founder ownership.
- Next Milestone Date: The precise date and time agreed upon for the subsequent conversation or deliverable submission.
When multiple co-founders participate in fundraising, assigning a single owner to each fund relationship is critical. If the Chief Executive Officer leads institutional narrative and the Chief Operating Officer handles operational proof points, the CRM must reflect who holds final responsibility for sending updates. This prevents duplicate outreach or conflicting messages from reaching the investment team.
Managing Cadence and Conversational Momentum Without Spamming
Fundraising momentum relies on steady, value-additive interaction rather than aggressive check-ins. Investors often evaluate dozens of active opportunities concurrently. If a founder sends repeated, unsubstantiated requests for updates, it signals desperation. Conversely, going silent for weeks causes deal momentum to dissipate.
To maintain professional cadence, every follow-up should deliver fresh operating evidence or directly address an open query from previous discussions. Acceptable follow-up triggers include:
- Delivering an agreed-upon diligence data point within twenty-four to forty-eight hours of a meeting.
- Announcing an audited monthly operating milestone, such as closing a flagship enterprise contract or exceeding gross merchandise value targets.
- Sharing relevant third-party validation, such as a published patent, regulatory clearance, or notable executive hiring.
The table below outlines an institutional follow-up schedule designed to sustain deal engagement while respecting investor evaluation timelines:
| Stage of Conversation | Appropriate Follow-Up Window | Recommended Communication Objective |
|---|---|---|
| Post-First Meeting | 24 hours | Send concise thank-you note, meeting summary, and requested supplementary documentation. |
| Awaiting Diligence Feedback | 4 to 5 business days | Provide a minor operating update while politely confirming whether additional analysis is required. |
| Post-Partner Pitch | 2 business days | Reiterate strategic alignment, clarify questions raised during the presentation, and confirm the investment committee schedule. |
| Term Sheet Deliberation | 48 hours | Address specific structural or governance points directly with the deal lead. |
Data Room Hygiene: Version Control and Phased Information Access
A disorganised data room undermines investor confidence during technical and commercial scrutiny. Distributing outdated financial models or mismatched cap tables creates immediate friction. Founders should establish a centralized, version-controlled repository structured according to institutional standards, as outlined in official Startup India pitch guidelines.
Implement strict naming conventions across all shared folders. File names should explicitly state document purpose, company identity, and release date (for example, Acme_Financial_Model_Q3_2026_v2.4.xlsx). Stale drafts must be archived immediately to prevent prospective backers from drawing conclusions from obsolete projections.
Furthermore, founders should verify that data room metrics reconcile perfectly with their startup financial projections and cap table records. Any discrepancy between introductory pitch decks and underlying spreadsheet ledgers triggers deeper diligence audits, prolonging the closing cycle unnecessarily.
Information Rights and Permission Tiers for Proprietary Data
Not every fund that requests diligence materials should receive unrestricted access to your complete operational architecture. Prematurely sharing source code repositories, unmasked customer lists, or proprietary unit margin breakdowns exposes your startup to significant competitive risk. Effective pipeline management incorporates tiered data room permissions based on relationship depth.
Organise diligence materials into three structured security tiers:
- Tier 1 (Introductory / Public Access): Pitch deck, high-level narrative summary, audited public case studies, and corporate entity verification. Provided after an initial introductory call.
- Tier 2 (Commercial Diligence): Historical profit and loss statements, unit economic cohort models, anonymised customer contract samples, and regulatory filings. Granted once an investor enters active partner diligence. Detailed requirements are catalogued in our startup due diligence checklist.
- Tier 3 (Confirmatory / Post-Term Sheet): Granular source code audits, unmasked customer reference contacts, detailed cap tables, and executive employment agreements. Shared only after an executed term sheet or formal investment committee approval.
Use secure data room software that allows founders to restrict file downloads, apply recipient watermarks, and revoke access permissions if a fund formally passes on the opportunity.
Opportunity Prioritisation: Scoring Depth, Velocity, and Fit
Treating every prospective backer with equal priority is an inefficient use of executive bandwidth. An active pipeline often contains dozens of leads, but only a fraction represent high-conviction matches capable of leading a round. Founders must score and rank prospects systematically inside their CRM.
Consider three key dimensions when evaluating pipeline priorities:
- Check-Writing Capacity & Thesis Fit: Does the fund lead rounds and write checks matching your current target tranche, or are they exclusively follow-on syndicators? Has their investment mandate supported your specific sector within the last twelve months?
- Partner Engagement & Seniority: Are you communicating directly with a General Partner possessing voting authority on the investment committee, or is an associate conducting exploratory market research without internal sponsorship?
- Process Velocity: Does the firm adhere to predictable evaluation timelines, or do they request open-ended data dumps over extended periods without committing to formal decision milestones?
Assign pipeline priority labels (Tier A, Tier B, Tier C). Allocate sixty to seventy percent of active meeting time and bespoke analysis to Tier A institutional leads, ensuring maximum momentum with high-conviction decision-makers.
Dissecting Interest: Separating Soft Commitments from Firm Term Sheets
A common operational pitfall for first-time founders is conflating verbal enthusiasm with committed institutional capital. An investor stating "we love the space and want to participate" has not made a binding commitment. In institutional venture capital, capital is uncommitted until formal legal instruments are executed.
Understanding the distinction between soft interest and binding commitments protects founders from prematurely shutting down their pipeline or celebrating unclosed rounds:
| Stage Parameter | Soft Expression of Interest | Firm Institutional Commitment |
|---|---|---|
| Document Status | Informal email exchange, verbal feedback over coffee, or non-binding interest memo. | Executed Term Sheet, Share Subscription Agreement, or binding side letter. |
| Conditionality | Contingent on finding an external lead investor, syndication partners, or further market checks. | Approved by formal Investment Committee; subject only to customary confirmatory legal diligence. |
| Capital Specificity | Vague check range (e.g., "We can do 1 to 3 Crores once your lead is set"). | Precise investment quantum, exact share class pricing, board seat terms, and clear closing timelines. |
| Pipeline Action | Keep investor active in diligence; continue pitching alternate lead prospects. | Move prospect to closing coordination; commence formal documentation workflows. |
As documented in state guidance on Startup India funding processes, formal financing rounds require precise legal instruments, board resolutions, and statutory filings rather than informal verbal accords.
Logging Rejections and Extracting Actionable Market Feedback
Rejection is an inevitable component of early-stage venture fundraising. Leading institutional founders frequently receive dozens of passes before securing lead terms. However, treating a pass as a dead record in your CRM wastes valuable market intelligence.
When an investor formally declines, record the stated rationale alongside an objective assessment in your CRM database:
- Thesis Misalignment: The fund does not back hardware, requires higher recurring revenue thresholds, or avoids specific regulatory structures.
- Portfolio Conflict: The firm previously invested in a direct or indirect competitor within the same operating geography.
- Metric or Valuation Gap: The investment team believes current customer acquisition costs, churn rates, or valuation expectations do not match their risk underwriting model.
If multiple independent funds raise identical concerns regarding gross margins, enterprise pilot conversion times, or ownership dilution detailed in your startup cap table guide, treat it as systemic operational feedback. Refine your narrative or adjust underlying operational targets before pitching the next batch of prospective investors.
Weekly Pipeline Review: Hygiene, Blockers, and Deal Flow Velocity
A fundraising CRM is only effective if audited continuously. Founders must institute a recurring, thirty-minute weekly pipeline review every Monday morning to maintain operational momentum across the entire syndicate.
During this review, evaluate your active funnel against four critical diagnostic questions:
- Which opportunities have stagnated? Identify any prospect that has remained in the same stage for more than ten business days without scheduled next steps.
- Where are diligence bottlenecks emerging? Determine whether pending action items (such as technical architecture deep-dives or customer references) are delaying investment committee reviews.
- Are pipeline conversions balanced? Ensure that as mature prospects move into partner meetings, fresh introductory conversations are entering the top of the funnel to maintain competitive tension.
- What are the critical deliverables for the coming week? Assign precise deadlines and founder ownership for every outstanding diligence item.
Maintaining weekly operational hygiene transforms fundraising from an ad-hoc distraction into an organized, high-velocity corporate initiative.
Hypothetical Case Study: Managing a 40-Investor Seed Pipeline in Bengaluru
The following fictional scenario illustrates how an Indian enterprise software startup applies structured CRM workflows during an active fundraising cycle. This example is purely hypothetical and intended solely to demonstrate pipeline mechanics.
Kavita and Rohan founded CloudBridge, a fictional B2B SaaS platform based in Indiranagar, Bengaluru. After validating product traction and building their initial shortlist, they launched a seed round targeting two million US dollars. Rather than managing investor interactions through disparate email threads, they deployed a standardized CRM tracking board.
| Pipeline Stage | Initial Prospects Count | Average Stage Velocity | Stage Exit Milestone |
|---|---|---|---|
| Lead Shortlist | 42 Funds / Angels | 3 Days | Warm connector identified and briefing note sent. |
| Intro Pitch Held | 28 Funds | 5 Days | Initial pitch deck reviewed; Tier 1 diligence access granted. |
| Active Diligence | 12 Funds | 12 Days | Cohort analysis evaluated; Tier 2 financial model provided. |
| Partner Committee | 5 Funds | 7 Days | Final partnership presentation completed. |
| Term Sheet Issued | 2 Funds | 4 Days | Commercial terms aligned; legal documentation commenced. |
During week three of their raise, Kavita noticed three Tier-A institutional funds had stalled in Active Diligence. Reviewing CRM interaction logs revealed that all three were waiting on customer reference calls. Rohan immediately coordinated with two enterprise design partners to establish dedicated reference slots. Within four days, two of those funds advanced to partner committee presentations, ultimately resulting in competitive term sheet proposals.
Founder Action Checklist: Daily and Weekly Pipeline Execution
Use this actionable operational checklist to maintain rigor across your active fundraising pipeline throughout the duration of your round:
- Daily Meeting Logging: Record comprehensive meeting notes, investor objections, and agreed deliverables within two hours of every pitch.
- Action Item Resolution: Fulfill all commitments (such as sharing data room models or scheduling follow-up technical sessions) within twenty-four to forty-eight hours.
- Permission Tier Audits: Verify that prospective investors receive appropriate data room tiers matching their current stage in the evaluation funnel.
- Weekly Funnel Review: Conduct a formal audit every Monday to clear deal blockers, review stage velocity, and re-prioritise high-conviction leads.
- Firm vs Soft Tracking: Maintain distinct CRM categories for soft interest versus binding term sheets to prevent premature closure of top-of-funnel deal flow.
- Post-Pass Archival: Record specific pass rationales for every declined lead, update the feedback log, and revoke data room access permissions promptly.
Take the next step
Running an organized, high-velocity fundraising pipeline requires structured preparation, clear documentation, and transparent execution. Whether you are preparing your initial data room or coordinating active partner diligence, RaiseMoney helps founders navigate every phase of the institutional fundraising journey.
Structure your active fundraising materials and connect with relevant institutional ecosystems by exploring our founder platform: Apply as a Founder on RaiseMoney.
Educational disclaimer
This article is published exclusively for general educational and informational purposes and does not constitute financial, investment, legal, or tax advice. Pipeline structures, conversion timelines, and data room frameworks vary based on specific corporate circumstances, prevailing market environments, and institutional fund mandates.
Sources
Frequently asked questions
What software should early-stage founders use for a fundraising CRM?
Founders can use specialized investor CRM tools, standard sales CRM platforms, or structured relational database spreadsheets. The specific tool matters far less than operational discipline: maintaining updated stage statuses, logging meeting notes promptly, tracking action items, and reviewing pipeline velocity weekly.
How often should founders update prospective investors during an active raise?
Touchpoints should be milestone-driven rather than time-arbitrary. High-priority leads in active diligence should receive agreed follow-ups within 24 to 48 hours. Leads evaluating materials can receive concise operating updates every 5 to 7 business days if meaningful progress occurs.
When is the right time to grant Tier 3 data room access?
Tier 3 materials containing unmasked customer contracts, source code architecture, or complete cap tables should only be unlocked after a fund has issued an executed term sheet or formally reached the confirmatory legal diligence stage.
How should founders handle an investor who expresses strong verbal interest but delays issuing a term sheet?
Treat verbal interest as uncommitted pipeline volume. Continue pitching alternate leads to maintain competitive momentum. Politely clarify the investor's remaining internal decision milestones and investment committee schedule while avoiding any pause in active deal flow.
What is the primary cause of pipeline stagnation during a raise?
Pipeline stagnation typically stems from unresolved diligence queries, lack of proactive founder follow-up, failure to establish clear stage exit milestones, or engaging with investment team members who lack internal sponsorship authority.