
Revenue recorded is not cash collected
A B2B startup can report growing revenue and still struggle to pay salaries because invoices remain unpaid. Accounts receivable is the amount customers owe for goods or services already billed. Invoice-to-cash is the operating path from agreed scope and delivery evidence through invoice issuance, customer approval, collection and bank reconciliation.
Founders should keep three numbers separate: revenue recognised under the company's accounting policy, invoices raised, and cash received. They can differ by period. An overdue invoice is not new revenue, and a promise to pay is not cash. This guide is therefore distinct from financial projections, burn rate and runway, and choosing a startup revenue model. Those tools forecast business performance and cash survival; receivables control explains why earned or billed money has not arrived.
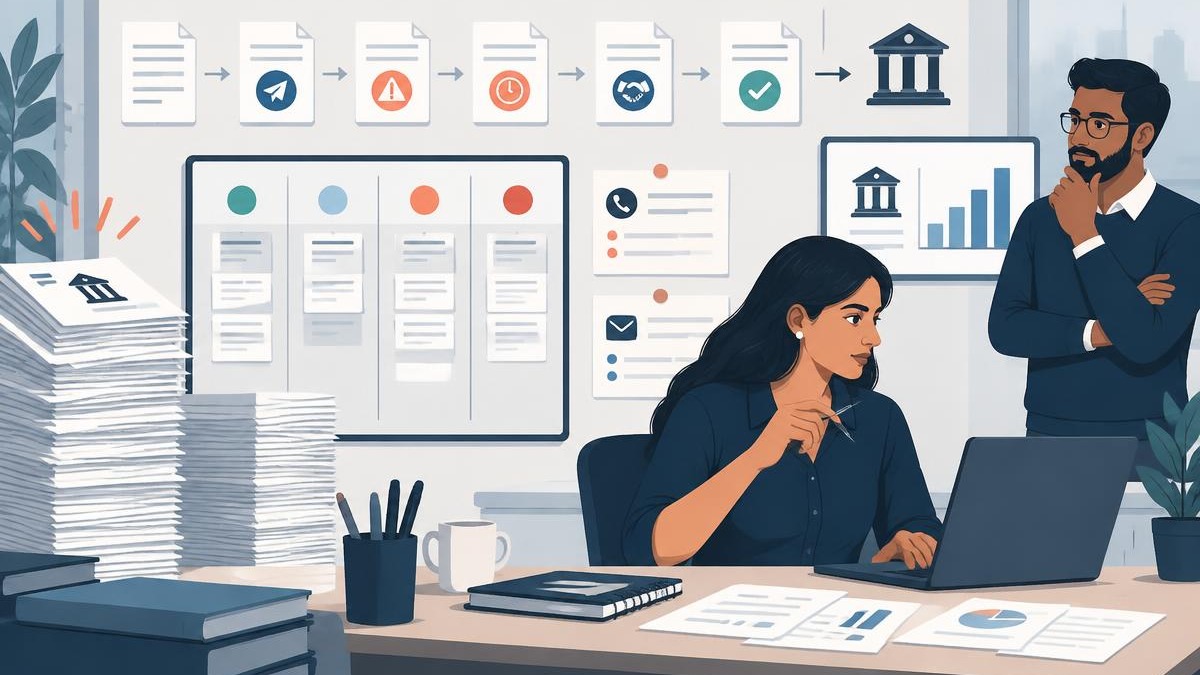
The process begins before invoicing. The contract, purchase order, tax details, acceptance criteria and payment terms determine whether the customer's accounts-payable team can process the bill. After delivery, someone must obtain acceptance evidence, create an accurate invoice, send it to the correct channel, confirm receipt, resolve holds, follow up and match the payment. If nobody owns those transitions, ageing grows even when customers intend to pay.
Design the invoice-to-cash path
Map the stages your team can observe: contract ready; purchase order received where required; delivery completed; acceptance documented; invoice prepared; invoice submitted; customer acknowledged; approved for payment; due; overdue; disputed; promised; paid; reconciled. A simple shared ledger is sufficient initially, provided every invoice has one status and one owner.
Capture customer legal name, tax details, billing address, purchase-order reference, invoice number and date, due date, amount, tax treatment confirmed by your adviser, submission channel, customer accounts-payable contact, business sponsor, dispute status, last action and next action. Rule 46 of the Central Goods and Services Tax Rules lists particulars for a tax invoice. Founders should use the current rule and professional advice for their facts rather than copy another company's invoice.
Submit promptly after the contractual billing event, but do not use an arbitrary universal deadline. A milestone invoice may need signed acceptance; a subscription may follow the agreement's schedule. Confirm that the client received the invoice in the required portal or mailbox. Sending it to the champion alone may not enter the payment workflow.
Separate responsibility. Finance owns ledger accuracy and reminders. The account owner helps remove relationship or delivery blockers. The founder handles material escalation and decisions about further service. One person can hold several roles in a small company, but the ownership must still be explicit.
Use ageing to decide, not merely report
An ageing view groups outstanding amounts by time. For daily management, choose practical buckets such as not due, 1-30 days overdue, 31-60, 61-90 and more than 90. These are internal operating choices, not universal legal thresholds. For statutory financial statements, Schedule III applicable to companies prescribes its own trade-receivables ageing presentation, including categories for disputed and undisputed balances. Your chartered accountant should confirm the applicable division and current presentation.
Age from the contractual due date when managing collections. Keep invoice date and due date separately so long payment terms do not look overdue before they are. Display disputed and undisputed amounts separately. Also show unbilled items separately; completed work awaiting a customer milestone or internal paperwork is a different problem from an issued invoice awaiting payment.
Review movements, not only totals. Which invoices entered a worse bucket? Which promised dates passed? Which customers repeatedly raise the same dispute? Which salesperson has contracts with unclear acceptance language? An ageing report becomes useful when it triggers an action.
A weekly review can assign each material item a next step: correct documentation, resend through the right portal, obtain acceptance, call accounts payable, involve the business sponsor, propose a payment plan, pause additional work under the contract, or seek professional advice. Do not threaten legal action casually. Escalation should follow the contract, evidence and value of the relationship.
Resolve disputes without hiding them
Disputes often begin with preventable gaps: the invoice does not quote the purchase order, the billed entity differs from the contracting entity, tax details are wrong, a milestone lacks acceptance, usage data cannot be reconciled, or work exceeds the written scope. Label the reason precisely. “Customer not paying” is not a diagnosis.
Open a dispute record with the amount challenged, amount undisputed, issue, evidence, decision owner and next review. Ask whether the customer can release the undisputed portion while the disputed balance is resolved. Do not alter or cancel an invoice without finance and tax review; the correct document depends on the facts.
The relationship owner should restate the disagreement neutrally and point to contract, purchase order, delivery note, usage record or acceptance email. If the startup is wrong, correct the error quickly and explain what changes. If the customer needs internal approval, identify the approver and missing evidence. If the dispute masks a product failure, route it to delivery rather than sending more reminders.
Track dispute value and age separately from ordinary overdue value. A ₹5 lakh invoice with ₹1 lakh disputed is not the same as ₹5 lakh undisputed and ignored. Recurring disputes reveal upstream defects. Feed those lessons into proposals, implementation scopes and handoffs. Better documentation reduces friction but cannot eliminate a genuine commercial disagreement.
Measure concentration alongside ageing
Receivable concentration asks how much outstanding money depends on one customer or a small group. A customer can be within terms and still create risk if a delayed approval would materially affect payroll. Calculate each customer's outstanding balance divided by total receivables, and review the top one, three and five. These are internal management measures, not mandatory thresholds.
Ind AS 107 requires applicable entities to disclose information about credit risk and concentrations, while Ind AS 108 includes major-customer disclosure for entities in its scope. Those standards do not turn a single percentage into a universal startup rule. Entity type and reporting framework matter. Use them as evidence that concentration is a recognised reporting concern, then let your finance adviser determine formal obligations.
Respond proportionately. For a concentrated customer, maintain more than one contact, confirm invoice acceptance, understand payment runs, avoid accumulating unapproved change work, and model a delay in the cash forecast. Consider deposits, milestone billing or shorter terms during the next negotiation if commercially realistic. Do not change signed terms unilaterally.
Concentration can be rational at an early stage. A large customer may provide learning and credibility. The decision is whether the startup knowingly accepts the cash-timing risk and has enough liquidity to carry it, not whether concentration can be removed immediately.
Worked INR example
Consider LedgerField, a hypothetical Indore B2B software company. At 30 September it has four invoices: Customer A owes ₹8,00,000, due 30 August; Customer B owes ₹5,00,000, due 15 September; Customer C owes ₹3,50,000, due 10 October; Customer D owes ₹1,50,000, due 25 September. Total receivables are ₹18,00,000.
Customer A disputes ₹2,00,000 but accepts ₹6,00,000. Customer B promises payment next cycle. Customer C is not due. Customer D has paid ₹1,50,000 on 29 September, but the bank receipt is not yet matched in the ledger. Before reconciliation, the ledger overstates receivables by ₹1,50,000.
After matching Customer D, true outstanding receivables are ₹16,50,000: ₹8,00,000 from A, ₹5,00,000 from B and ₹3,50,000 from C. Amount overdue is ₹13,00,000 because C is not due. Of overdue value, ₹2,00,000 is disputed and ₹11,00,000 is undisputed. Customer A represents 48.5% of outstanding receivables: ₹8,00,000 divided by ₹16,50,000. That concentration deserves founder attention even though part is acknowledged.
The action list is specific. Finance requests release of A's ₹6,00,000 undisputed balance while delivery resolves the ₹2,00,000 issue. The account owner confirms B's exact approval status and promised date. C receives no overdue chase, but its submission is checked before due date. D is closed after reconciliation.
If September revenue was ₹20,00,000, none of these balances should be described as another ₹16,50,000 of revenue. They are cash claims already arising from prior recognition or billing. Management reporting should show revenue, invoicing, collections, ending receivables, overdue receivables and disputes separately.
Create a collection cadence based on status
Use event-based follow-up rather than aggressive repeated reminders. Before due date, confirm invoice acceptance where the customer's process warrants it. On the due date, check whether approval is complete. After the due date, ask for the blocker and a specific next action. When a promised date passes, escalate to the business sponsor with the record attached.
Messages should identify invoice number, amount, due date and requested action. Avoid copying large groups before understanding the issue. Keep a log because staff changes and verbal promises are common. If a customer repeatedly pays late, address terms at renewal or before taking additional scope.
Do not make legal-interest, MSME or tax assertions from memory. The Micro, Small and Medium Enterprises Development Act has specific provisions and disclosures, but applicability and remedies depend on the supplier's status and current law. Obtain qualified advice before adding interest, issuing a legal notice or making a statutory claim. The same caution applies to e-invoicing thresholds, which can change by notification.
Close the loop when cash arrives. Match bank receipt to invoice, investigate deductions, update the ledger and tell the account owner. Unapplied cash can make the customer appear overdue and trigger an avoidable escalation.
Founder action checklist
- Map every stage from contract and acceptance to bank reconciliation.
- Give every invoice a due date, status, owner and next action.
- Confirm current invoice particulars with your tax adviser.
- Review not-due, overdue, disputed and unbilled amounts separately.
- Ask for undisputed portions to be released where appropriate.
- Calculate top-customer and top-five concentration monthly.
- Track promises and escalate missed dates with evidence.
- Reconcile bank receipts before reporting the closing balance.
- Show revenue, invoices, collections and receivables as separate figures.
- Feed repeated disputes back into contracts and delivery records.
A good receivables process does not guarantee customers pay on time. It makes delay visible early, assigns the response and prevents accounting labels from hiding a cash problem.
Take the next step
If your B2B startup needs a clearer operating and fundraising story, apply as a founder. Application does not promise collection outcomes, admission or investment.
Educational disclaimer
This article is general education, not accounting, tax or legal advice. Reporting standards and invoice rules depend on entity and transaction facts. Consult qualified Indian professionals before acting.
Sources
Sources reviewed 23 September 2026.
Frequently asked questions
What is accounts receivable?
It is money customers owe for billed goods or services that has not yet been collected.
Is every outstanding invoice overdue?
No. An invoice is outstanding until paid, but it becomes overdue only after its contractual due date.
Who should own collections?
Finance should own ledger accuracy and routine follow-up, the account owner should remove relationship blockers, and founders should handle material escalation.
How should a disputed invoice be shown?
Track disputed and undisputed portions separately, with evidence, owner and next action. Ask about release of the undisputed part where appropriate.
What is receivables concentration?
It is the share of total outstanding receivables attributable to one customer or a small group, useful for understanding cash-timing risk.
Is ageing a legal requirement for every startup?
Schedule III applies to companies preparing relevant financial statements, while entity-specific obligations vary. Ask a chartered accountant about your reporting framework.